 BrazilA leading bankUp to 15% fewer losses on its riskiest business customers, at the same approval rate.Up to 15%fewer losses in the riskiest band, at the same approval rateRead the story
Business credit scoring for businesses that are hard to underwrite.
Shops, traders, sole proprietors and new companies often come with no credit file, thin statements and little paperwork, so lenders turn good businesses away or price them all as risky. Monnai reads the owner’s phone and email and how the business shows up online, and scores them more accurately.
Up to 15%fewer losses on its riskiest business customersA leading bank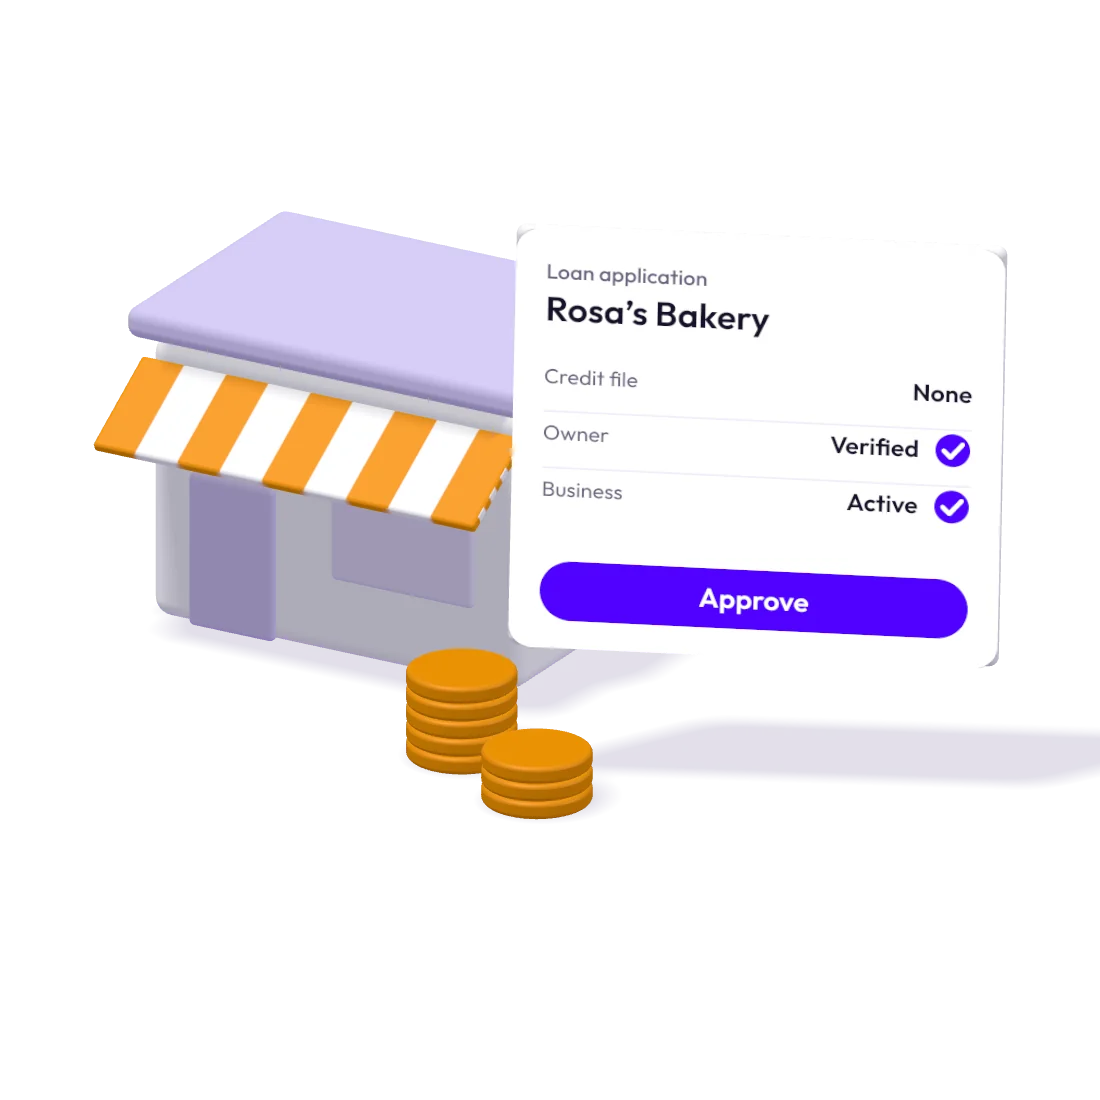
Why businesses are hard to underwrite, and how Monnai scores them.
No file, no statements, no history.
Is the business even real?
Manual reviews slow every decision.
Business credit scoring results: where Monnai adds the most.
From a proof of concept with a leading bank in Latin America: the gain measured on months the model had never seen, and how Monnai sorts the businesses the bank knows least.
- Thin-file, higher-risk businesses+21%
- Health services+17%
- Auto trade and repair+12%
- Sole proprietors+6%
- All businesses+5%
- AUnder 1%
- B1%
- C3%
- D4%
- E7%
- F11%
- G18%
- H31%
- Approve41% automatically
- Review or collateral47%
- Decline, with reasons12%
Charts from the customer’s proof-of-concept report, anonymized and rounded.
Customer results in business lending.
What they needed, and what they measured.
BrazilA leading bankUp to 15% fewer losses on its riskiest business customers, at the same approval rate.Up to 15%fewer losses in the riskiest band, at the same approval rateRead the story North AmericaA merchant platformGood merchants start selling sooner. Bad ones never get in.88%of risky merchants stopped before they go liveRead the story
Get answers about business lending
What is business credit scoring with alternative data?
It means scoring a business from more than a credit file and statements, which many small businesses don’t have. Monnai starts with the owner’s phone, email and digital footprint and ranks every application by risk from day one. Business Web Presence adds how the business shows up online.
How can lenders check that a small business is real?
Shell companies and fake shops borrow once, then disappear. Business Web Presence reads how a business shows up online, what its customers say and what it really sells, and flags a website only weeks old, a parked domain or a burst of reviews in one day.
How can lenders cut manual review on small business loans?
Manual review eats the margin on small loans. Rank every application by risk from day one: Risk Score gives each one a number from 0 to 999, where higher means riskier, with up to five reasons, and you set where approve, review and reject start.
Does Monnai replace registry checks and credit files?
No. It adds to them. Where a registry record or a credit file exists, keep using it; where it doesn’t, the owner’s phone, email and digital footprint still give you something to score. Monnai’s fields and Risk Score feed your own decision engine.
How do we test business credit scores on our own portfolio?
Send past applications, with or without repayment outcomes. We score them offline, with no integration on your side, and your full report comes back within 5 business days: every score with its reasons, and the uplift for your portfolio when you share outcomes.
Let us prove it. Test us on your data.
Send past applications or transactions. We score them and send back a full report: every score with its reasons, and the uplift for your portfolio.
5 business days to your full report. We commit to it.